Physician Financial Advisors
Helping you build and protect your lifetime of work.
Fiduciary financial and tax planning education for residents, fellows, and physicians.
Financial health is akin to your physical or mental health. A lot of factors are at play, but with education, experience, and the right guidance you can learn to manage most of it on your own.
That’s why we educate our physicians first and empower them to create financial security for themselves and future generations.
Watch, Do, Teach, Repeat.
Fiduciary standard
Your interests come first. That is an obligation, not a preference.
How we work togetherLed by CFP® professionals
Every plan is led by a CERTIFIED FINANCIAL PLANNER® professional, held to CFP Board’s Code of Ethics and Standards of Conduct.
Meet the teamBuilt for medicine
Intern year to practice ownership: loans, contracts, own-occupation disability, and the first attending tax year.
How it worksstart where you are
Pick your stage. We’ll show you the five decisions that matter most right now.
What do you want to learn about?
Search for anything, or check the areas that matter to you right now.
Your topics
How it works
The way you learned medicine. The goal is that you need us less over time, not more.
Watch
Start with the education here, then two free meetings. We map where you are, what changes this year, and what can wait.
Meetings 1–2: Introduction, Deep Dive Discovery
Do
Together we build the plan and work it one area at a time: insurance, investments, tax, benefits, estate. You do it with a planner beside you, not for you.
Meetings 3–9: Clarity through Estate Planning
Teach
You understand every decision well enough to explain it to a co-resident. Education sessions go deeper wherever you want them.
Education sessions, on request
Repeat
Fellowship, first contract, partnership, practice ownership. Each year closes with a recap and renewal, and the cycle begins again with you further ahead.
Meetings 12–13: Wrap-up, Recap & Renewal
Residency programs: invite us to noon conference
A 45-minute talk on the money decisions of training. No product pitch. Program coordinators and chief residents can book one directly.
Our process
Twelve months. Ten to twelve hours of meetings, one area at a time. The first two meetings are free; the engagement begins after them, if we both decide to go forward.
Getting to know you
Free. No commitment.
- Introduction30 min
- Deep Dive Discovery90 min
Your plan
The engagement begins here.
- Clarity Meeting60 min
- Financial Plan & Executive Summary60 min
One area at a time
Each meeting works one part of the plan.
- Insurance Planning60 min
- Investment Planning60 min
- Tax Planning60 min
- Open Enrollment & Stock Option Planning60 min
- Wills, Trusts & Estate Planning60 min
- Children, Education & Generational Wealth Planning optional60 min
- Real Estate Education optional60 min
Keeping it current
Close the year, plan the next.
- Updates & Wrap-up60 min
- Recap & Renewal60 min
Education sessions you can request
Sixty-minute working sessions, added to the engagement whenever a topic becomes real for you.
- Benefit planning and open enrollment assistance
- Stock option planning and vesting-period assistance
- Medicare, Social Security, and retirement income distribution strategies
- Leveraging assets and accessing available lines of credit
- Managing debt: student loans, credit cards, and paydown strategies
Your first attending paycheck
The most important number in a physician’s financial life is the gap between a resident’s take-home pay and an attending’s. See yours, and decide where it goes before it arrives.
Your numbers
Monthly take-home
If you keep living like a resident
Hold a resident’s budget for two or three years after training and the gap does the work. Before any investment growth:
What this assumes
- 2026 federal brackets and standard deduction (single $16,100; joint $32,200); no itemized deductions or credits.
- Social Security tax of 6.2% up to $184,500 of wages; Medicare 1.45%, plus 0.9% above $200,000 (single) or $250,000 (joint).
- Pre-tax retirement deferrals reduce federal and state taxable income but not Social Security or Medicare wages.
- State tax is your entered effective rate applied to wages after deferrals. Local taxes, health premiums, and other payroll deductions are not included.
Estimates for education only, not tax advice. Your actual withholding and liability depend on your full return; confirm with a tax professional.
Two pages that cover intern year to first contract
The checklist we walk every resident through. Print it, tape it inside a locker, cross things off. We’ll email you when it changes, and nothing else.
Insights
Longer reads on the decisions that matter most, written for physicians and free of product pitches.
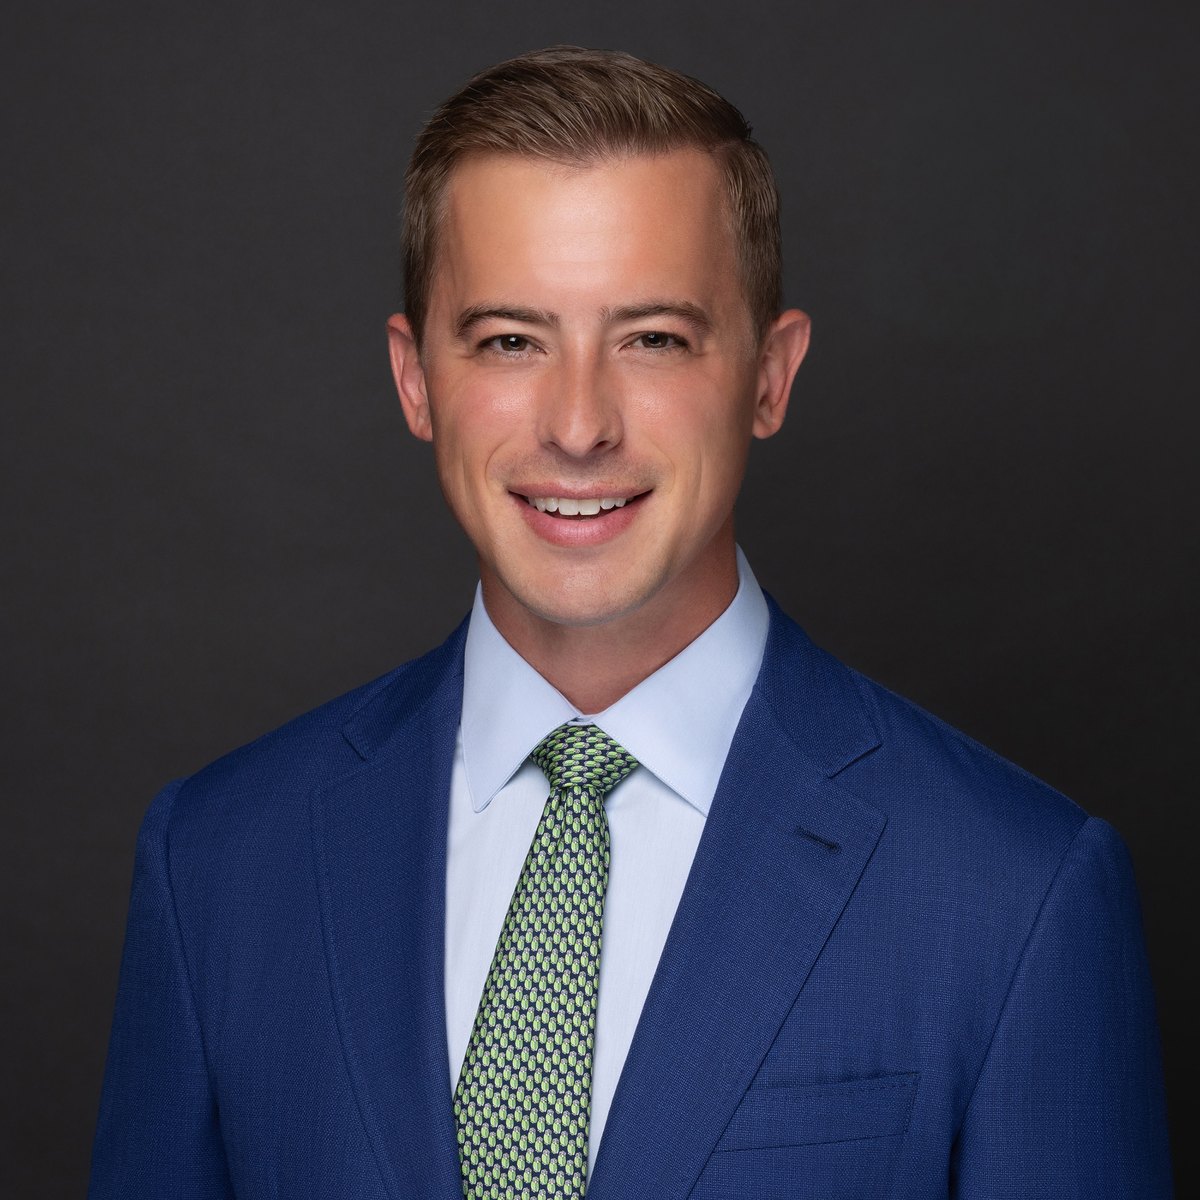
Stratton GrandyCFP®, ChFC®
Director of Business Development, GBP Wealth Management
Physician Financial Advisors works with residents, fellows, and attending physicians on the decisions that shape a medical career: disability coverage, student loans, the first contract, the first attending tax year, and the habits that turn a high income into lasting security.
The approach is the one you already know. Watch, do, teach, repeat. You should understand every decision well enough to explain it to a colleague, so that over time you need us for the hard questions and not the routine ones.
Backed by a Northwestern Mutual Private Client Group team
Physician Financial Advisors is the physician practice of GBP Wealth Management, a Northwestern Mutual Private Client Group firm focused on complex wealth, business, and estate planning. When a plan needs more than one set of hands, the rest of the team is already in the room.
Stratton is the point of contact for every physician engagement. Todd and Chuck join when a plan calls for them.
Verify any advisor before you work with them. Look up their record on FINRA BrokerCheck and confirm CFP® certification at CFP.net. Registration details are on our disclosures page.
How we work together, and other fair questions
Physicians read the fine print. Here it is, up front.
Three ways to engage
Everything on this site is free, and always will be. When you want the firm in the room, the engagement takes one of three forms. You have the terms in writing before anything begins.
- Flat fee. A 12-month engagement that retains our firm as your fiduciary financial consultants. You receive a comprehensive financial plan, built out with guidance, education, and recommendations across every area on this page.
- Advisory. A fee on assets actively managed on our platform, on this schedule:
Advisory fee schedule Assets managed Annual fee $0 – 2 million 1.00% $2 – 5 million 0.75% $5 – 15 million 0.50% $15 – 20 million 0.45% $20 – 30 million 0.40% $30 – 50 million 0.35% $50 – 100 million 0.30% $100 million and above 0.25% - Insurance. When a policy is the right tool, we place it. The firm is licensed to write insurance in all 50 states, and you see the cost, the reason, and the alternative before you buy.
The fiduciary standard, plainly
When we provide financial planning and investment advice, we are obligated to act in your best interest, and CFP® professionals are held to CFP Board’s fiduciary duty whenever they give financial advice. Insurance recommendations are held to the best-interest standards that apply to that role.
Two commitments in either role: we tell you which one we are in, and we never recommend anything we could not explain to a room full of your colleagues.
Frequently asked
Are you a fiduciary?
When we provide financial planning and investment advice, yes. We are obligated to put your interests first, and CFP® professionals are bound by CFP Board’s fiduciary duty whenever they give financial advice. When a recommendation involves an insurance policy, that part of the work is governed by the best-interest standards that apply to insurance, and we tell you when we are in that role.
In plain terms: you will always know which hat we are wearing and how the work in front of us is paid for.
Will I be pitched whole life insurance?
Insurance is sometimes the right tool. Own-occupation disability coverage almost always is for a physician in training, and term life usually is once someone depends on your income. Permanent life insurance fits a narrow set of situations, and for a resident carrying loans it is almost never the first, second, or third move.
When we recommend a policy, you get the cost, the reason, and the alternative in writing before you decide.
I’m a resident. Can I afford this?
Everything on this site is free, and it is designed to carry you through most of training. So are the first two meetings. When you want the firm in the room for a full year, the flat-fee engagement is quoted in writing before you commit.
Do I have to be in a particular state?
No. We work with physicians in all 50 states, by video and phone. The firm is licensed to write insurance in every state, and we are licensed to provide investment services in every state as well. Training in one state and practicing in another changes nothing about how we work together.
What is a CFP® professional, and why does it matter?
CERTIFIED FINANCIAL PLANNER® certification requires a bachelor’s degree, a board-registered education program, a comprehensive exam, thousands of hours of documented experience, a background check, and continuing education. CFP® professionals commit to CFP Board’s Code of Ethics and Standards of Conduct, including a fiduciary duty when providing financial advice. Verify anyone’s certification at CFP.net.
How is this different from reading White Coat Investor?
It is not a substitute. The philosophy here is the same one you will find in the best physician finance writing: protect your income, retire the debt, keep costs low, automate, and do not buy what you do not understand. The difference is a person who knows your contract, your loans, your state, and your family, and who is accountable to you for the plan.
Watch, do, teach, repeat. Success means you could run most of this yourself and choose to keep us for the hard parts.
What happens on the first call?
Thirty minutes, free. You describe where you are and what is on your mind; we ask about loans, coverage, contract timing, and family, and explain how the engagement works. If it makes sense to continue, the second meeting is a 90-minute Deep Dive Discovery, also free. You leave both with things to do whether or not we ever speak again. Nothing to sign, nothing to buy.
Can you speak to our residency program?
Yes. We give a 45-minute noon-conference talk on the money decisions of training, with no product pitch. Program coordinators and chief residents can request a date here.
Talk to a CFP® professional
Bring your questions. A fiduciary planner who works with physicians will answer them plainly. No obligation; residents and fellows welcome.
Send a message
We reply within one business day.
Message sent.
Thank you. You’ll hear back within one business day with a few times to talk. If it’s time-sensitive, email directly at stratton.grandy@nm.com.
Or email directly
Every message is read by a CFP® professional, and we reply within one business day with a few times to talk, by video or phone, around your shifts.